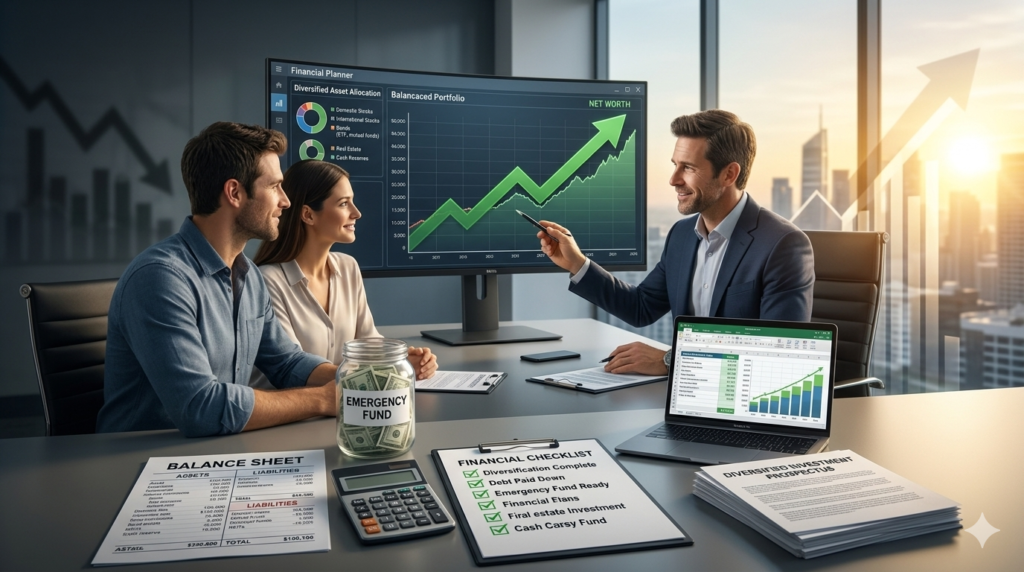
What Determines Personal Wealth? Personal wealth depends on the value of your assets, outstanding liabilities, income, saving habits, investment returns, and financial decisions. Your net worth is calculated by subtracting total liabilities from total assets. Although income can help you accumulate wealth, spending, debt management, inflation, and long-term financial planning also influence how much wealth you build.
Introduction: Why Do Some People Build Wealth Faster Than Others?
Why do some people accumulate wealth over time while others struggle financially despite earning a decent salary? The answer is more complicated than simply earning more money. Financial stability and long-term wealth depend on how people earn, spend, save, invest, and manage their financial responsibilities.
Understanding what determines personal wealth can help you make informed decisions about your money. Your salary matters, but it does not tell the whole story. Someone with a moderate income, controlled expenses, manageable debt, and consistent investments may gradually build a stronger financial position than someone who earns considerably more but spends everything they make.
Personal wealth is commonly measured through net worth, which represents the difference between everything you own that has financial value and everything you owe. However, wealth accumulation also depends on your financial circumstances, access to opportunities, family resources, and the economic environment.
This guide explains the major factors influencing personal wealth, shows you how to calculate your net worth, and provides practical steps you can take to improve your financial position.
Why Am I Not Building Wealth Despite Earning Money?
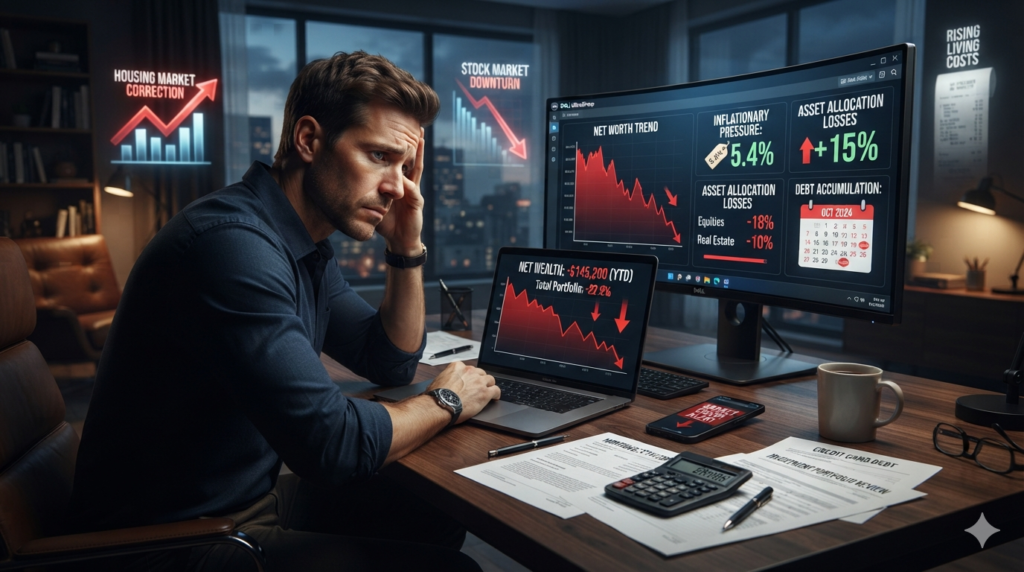
Earning money is an important starting point, but income alone does not guarantee financial progress. If most of your earnings disappear into everyday expenses, debt payments, and lifestyle upgrades, your net worth may remain unchanged.
Three common factors can explain why your financial progress feels slower than expected.
How Income and Earning Potential Affect Wealth
Income determines how much money you have available to cover expenses, repay debt, save, and invest. Higher earnings can create more opportunities to accumulate assets, particularly when your spending does not increase at the same rate.
Income may come from several sources, including:
- Employment salaries and wages.
- Business profits and self-employment.
- Freelance work and consulting.
- Rental income and certain investment distributions.
- Royalties or other income-producing assets.
Increasing your earning potential through professional training, valuable skills, career development, or business opportunities can improve your financial flexibility.
However, earning more is only part of the equation. The amount you retain and use to build assets also matters.
How Spending Behavior and Lifestyle Inflation Reduce Savings
Lifestyle inflation occurs when your expenses rise as your income increases. For example, you might receive a salary increase but immediately upgrade your vehicle, move into a more expensive home, or increase discretionary spending.
Although these choices may improve your lifestyle, they can prevent your financial position from improving.
Consider someone whose monthly income increases from $3,000 to $4,000. If monthly expenses rise from $2,700 to $3,800, their monthly surplus increases by only $100, despite earning an additional $1,000.
Keeping some expenses stable when income rises can help you direct more money toward savings, debt repayment, and investments.
How Debt Management Strategies Help Build Financial Stability
Debt can reduce your ability to accumulate wealth because repayments consume income that could otherwise be saved or invested. High-interest credit card balances and expensive consumer loans can be particularly difficult to manage.
To improve your position:
- List all outstanding debts and their interest rates.
- Prioritize expensive debt while maintaining required payments on other obligations.
- Avoid accumulating new high-interest balances.
- Consider refinancing only after comparing fees, terms, and total borrowing costs.
- Maintain appropriate emergency savings so unexpected expenses do not force you into additional debt.
Debt is not always harmful. A manageable mortgage or a carefully considered education loan may support long-term goals. What matters is whether the borrowing cost, repayment obligations, and associated risks are appropriate for your circumstances.
What Determines Personal Wealth and Why Do Some People Build Wealth Faster?
Several connected financial factors determine how much wealth a person accumulates. Understanding their relationship helps explain why two people with similar incomes can have very different net worths.
How Assets and Liabilities Determine Your Net Worth
Assets are things you own that have financial value. Liabilities are financial obligations you owe to other people or institutions.
Common assets include:
- Cash and savings accounts.
- Stocks, bonds, and investment funds.
- Retirement and pension account balances, where applicable.
- Real estate and other valuable property.
- Ownership interests in businesses.
Common liabilities include mortgages, student loans, personal loans, vehicle loans, and unpaid credit card balances.
Your net worth reflects the difference between these two categories. A person may own a valuable house but have a relatively modest net worth if the mortgage balance is substantial.
It is also important to distinguish net worth from available cash. Property and retirement investments may contribute to wealth but cannot always be accessed immediately without costs, restrictions, or taxes.
How Investment Returns Over Time Increase Wealth
Investments can help wealth grow through price appreciation, interest, dividends, and reinvested earnings. The results depend on the investment, its costs, market conditions, and the amount of time the money remains invested.
For example, investing consistently over many years may allow your contributions and their accumulated returns to work together. However, investment values can fall, and positive returns are never guaranteed.
A longer time horizon can give investments more opportunity to compound, but it does not eliminate risk.
How Financial Literacy and Education Improve Financial Decisions
Financial literacy means understanding basic financial concepts and applying them to everyday decisions.
Useful financial skills include:
- Preparing and reviewing a budget.
- Understanding interest rates and loan terms.
- Comparing investment costs and risks.
- Building emergency savings.
- Recognizing the effects of inflation.
- Evaluating financial products before committing money.
You do not need to become a professional financial expert to improve your financial decisions. Learning the basics and consistently applying them can help you avoid costly mistakes and make better use of the resources available to you.
How Is Personal Wealth Calculated?
Personal wealth is commonly measured using net worth. The calculation is straightforward: identify the current value of your assets, calculate your outstanding liabilities, and subtract the second amount from the first.
Net Worth = Total Assets − Total Liabilities
A positive result means your assets exceed your liabilities. A negative result means your liabilities exceed your assets.
How to Complete a Personal Net Worth Calculation
Follow these steps to calculate your personal net worth.
Step 1: List your assets. Include your cash, bank balances, investments, retirement accounts, property equity components, and other assets with measurable financial value.
Step 2: Estimate current values. Use current account balances and reasonable market estimates rather than original purchase prices.
Step 3: List your liabilities. Record outstanding mortgage balances, credit card debt, personal loans, vehicle loans, and other amounts owed.
Step 4: Add your totals. Calculate the combined value of all assets and all liabilities separately.
Step 5: Subtract liabilities from assets. The result is your estimated net worth.
How Compound Interest and Wealth Accumulation Work
Compound growth occurs when investment earnings remain invested and can generate additional earnings. Over time, this may accelerate the growth of an investment portfolio.
For example, suppose you invest $200 every month for 20 years and earn a hypothetical annual return of 6%, compounded monthly. Assuming contributions are made at the end of each month, the account could grow to approximately $92,400 before fees and taxes.
Your total contributions would be $48,000, meaning the remaining balance would represent investment growth.
This is an illustration, not a prediction. Actual returns fluctuate, investments may lose value, and fees, taxes, and inflation can affect the final result.
Assets, Liabilities, and Net Worth Examples
The following example shows how a household might calculate net worth.
| Financial item | Category | Example value |
|---|---|---|
| Bank savings | Asset | $8,000 |
| Investment portfolio | Asset | $12,000 |
| Home market value | Asset | $180,000 |
| Vehicle market value | Asset | $15,000 |
| Mortgage balance | Liability | $145,000 |
| Vehicle loan | Liability | $7,000 |
| Credit card balance | Liability | $3,000 |
| Total assets | $215,000 | |
| Total liabilities | $155,000 | |
| Net worth | $60,000 |
In this example, total assets are $215,000 and total liabilities are $155,000. Subtracting liabilities from assets produces a net worth of $60,000.
If the household repays $2,000 of debt using existing cash, its net worth generally remains unchanged immediately because cash and liabilities both decrease by $2,000. However, future interest costs may fall, helping the household retain more money over time.
This distinction is important: paying debt improves net worth directly when the payment is made from income or other resources without an equivalent reduction in existing assets, or when interest and other costs are avoided over time.
Does Income Determine Personal Wealth?
Income plays an important role in wealth accumulation, but it does not independently determine a person’s net worth. Two people earning the same salary can have different financial outcomes because of their expenses, debt, savings, investments, and starting circumstances.
How Your Career Affects Wealth Over Time
Your career can influence both your current income and future earning potential. Skills that are in demand, professional experience, entrepreneurship, and opportunities for advancement may increase earnings over time.
Employment can provide predictable income, while self-employment and business ownership may offer greater earning potential alongside greater uncertainty.
The best financial strategy depends on your circumstances. Improving skills, negotiating compensation when appropriate, and developing additional income sources may strengthen your financial position, but no career path guarantees wealth.
Does Saving More Build Wealth Than Earning More?
Both higher income and effective saving can contribute to wealth accumulation.
Imagine two people who each earn $4,000 per month. One spends $3,800 and saves $200, while the other spends $3,000 and saves $1,000.
The second person saves $800 more each month despite earning the same amount.
Increasing income can make a significant difference, especially when essential expenses already consume most of your earnings. The strongest approach is often to improve earning potential while maintaining a sustainable gap between income and expenses.
How Do Assets Increase Net Worth?
Assets can contribute to wealth through appreciation, income generation, or the accumulation of savings and investments.
For example, investments may increase in value, rental property may produce income, and cash savings may provide financial security. A business may also become more valuable as its profits and prospects improve.
However, asset ownership involves costs and risks. Property requires maintenance and may be difficult to sell quickly, while investments can decline in value. Evaluate the net financial benefit rather than assuming that every asset will increase in value.
How Does Debt Affect Personal Wealth?
Debt influences personal wealth through outstanding balances, interest costs, required payments, and the opportunities those obligations may prevent you from pursuing.
Which Liabilities Have the Biggest Impact on Net Worth?
The impact of debt depends on its balance, interest rate, repayment schedule, and purpose.
High-interest credit card debt can be particularly expensive because interest charges may accumulate quickly. Personal loans and vehicle financing can also create substantial monthly obligations.
Mortgages and student loans require a more individual assessment. They may finance housing or education that supports important long-term goals, but their affordability depends on borrowing costs, income, and repayment terms.
How Debt Repayment Can Improve Your Financial Position
Reducing debt can improve financial resilience by lowering required payments and reducing future interest expenses.
For example, paying off a high-interest credit card balance can free up money that would otherwise go toward interest. Once the balance is reduced, you can redirect that money toward emergency savings or investments.
Make minimum required payments on all debts, then consider prioritizing the highest-interest balance to reduce borrowing costs. Alternatively, some people prefer paying smaller balances first to build momentum. Choose an approach you can maintain.
How to Balance Debt Repayment and Investing
The decision to repay debt or invest depends on several factors.
Consider the interest rate on your debt, your emergency savings, employer retirement contributions where available, investment time horizon, and tolerance for financial risk.
Paying off high-interest debt can provide a relatively predictable saving in interest costs. Investment returns, by contrast, are uncertain. At the same time, investing for retirement or obtaining an available employer contribution may be valuable in some circumstances.
There is no universal answer. Compare the costs, benefits, liquidity needs, and risks before deciding how to divide your available money.
How Does Investing Grow Wealth Over Time?
Investing can help you build wealth by putting money into assets that may generate income or appreciate in value. The appropriate investment strategy depends on your goals, financial situation, time horizon, and risk tolerance.
How Compound Interest Supports Long-Term Wealth
Compounding allows investment earnings to generate additional earnings when they remain invested.
Suppose an investment of $10,000 grows at a hypothetical annual rate of 5%, compounded annually. After 10 years, it would be worth approximately $16,289 before fees, taxes, and inflation, assuming the same return every year.
The additional value comes from the original investment and the accumulated growth.
Real investment returns do not follow a fixed path. Compounding illustrates the potential benefit of time, not a guarantee of future results.
How Financial Risk and Diversification Affect Investments
Every investment involves some combination of risk, uncertainty, and potential return. Shares can fluctuate significantly, bonds can lose value, and property can be affected by local economic conditions.
Diversification means spreading investments across different assets, industries, companies, or geographic markets rather than relying heavily on a single investment.
A diversified portfolio can reduce the impact of some investment-specific losses, although it cannot eliminate market risk.
Consider the following principles:
- Match your investment choices to your financial goals.
- Avoid investing money you may need immediately in volatile assets.
- Review investment fees and tax implications.
- Understand the risks of every investment before buying.
- Reassess your portfolio when your circumstances or goals change.
How Real Estate and Asset Ownership Contribute to Wealth
Real estate can contribute to wealth through property appreciation, rental income, and the gradual repayment of a mortgage.
For example, a property owner may build equity as the mortgage balance decreases. If the property’s market value also rises, equity may increase further.
However, property ownership involves maintenance, insurance, taxes, transaction costs, and potential vacancies. Property values can fall, and selling a property can take time.
Real estate should therefore be evaluated according to its overall costs, income potential, liquidity, and suitability for your financial circumstances.
How Does Inflation Reduce Personal Wealth?
Inflation is the general increase in prices over time. It affects personal wealth because money gradually loses purchasing power when prices rise faster than the money’s value or income.
How Cost of Living and Inflation Affect Purchasing Power
Imagine that your monthly household expenses are $2,000 today. If the relevant prices increase by 4% over a year, maintaining the same spending pattern would cost approximately $2,080.
If your income remains unchanged, you have less money available for savings and investments.
Inflation can also reduce the real value of cash savings. Although the amount in a savings account may remain unchanged, that money may buy fewer goods and services in the future.
How to Protect Your Financial Goals From Rising Expenses
You cannot control overall inflation, but you can take steps to manage its effects.
Review your budget regularly, compare essential expenses, avoid unnecessary recurring costs, and adjust savings targets when your circumstances change.
An emergency fund can help you handle unexpected expenses without relying on expensive debt. Depending on your goals and risk tolerance, a diversified long-term investment strategy may also help you pursue growth that keeps pace with or exceeds inflation over time.
How to Evaluate Wealth Growth After Inflation
Nominal growth describes the increase in the stated value of your money or investments. Real growth accounts for changes in purchasing power.
For example, if an investment grows by 6% in a year while inflation is 3%, its approximate real return is 3%. The precise real return is slightly lower, at about 2.9%, before fees and taxes.
This difference matters because a larger account balance does not necessarily mean you can afford substantially more goods and services.
When evaluating long-term financial progress, consider both changes in net worth
How Do Inherited Wealth and Family Assets Affect Net Worth?
Personal wealth does not always begin with income earned through employment or business. Family support, inherited property, gifts, and other intergenerational resources can influence a person’s starting financial position.
How Inherited Wealth and Family Assets Create Financial Advantages
An inheritance may include money, investments, real estate, or ownership in a family business. These assets can reduce the need to borrow, provide financial security, or create opportunities for further investment.
Family assistance can also take less direct forms, such as help with education, housing costs, or business startup expenses.
These advantages can make it easier for some people to accumulate wealth. However, inheritance is not guaranteed to produce lasting financial security. Asset maintenance, taxes, poor investment decisions, and excessive spending can reduce inherited wealth.
How Financial Habits Influence Wealth Across Generations
Financial habits and knowledge can influence how families preserve and transfer assets.
Teaching younger family members about saving, budgeting, borrowing, and responsible investing can help them make informed decisions. Open conversations about financial responsibilities may also prepare future generations to manage inherited assets effectively.
Financial education cannot eliminate every economic challenge, but it can improve decision-making and reduce avoidable mistakes.
Can You Build Wealth Without Inheritance?
Yes. Inheritance is one possible source of wealth, not a requirement for building it.
People may accumulate assets through employment, business ownership, saving, investing, and responsible debt management. Progress can be gradual, and individual outcomes depend on factors such as income, living costs, access to opportunities, family responsibilities, and economic conditions.
It is important to recognize that people do not all start from the same financial position. Focus on realistic improvements within your control rather than comparing your progress with someone who has different resources or obligations.
How Can I Improve My Net Worth Starting Today?
Understanding wealth is useful, but applying that knowledge to your financial life is what makes it practical. You can begin with a simple review of your current position and build a plan that fits your circumstances.
Create a Monthly Personal Net Worth Checklist
Use this checklist at the end of each month or quarter.
- Record your current bank and savings balances.
- Update the value of your investments and other assets.
- Record outstanding loans and credit card balances.
- Calculate your total assets and liabilities.
- Subtract liabilities from assets to find net worth.
- Review your monthly savings and debt repayments.
- Identify one realistic improvement for the next month.
Tracking your net worth consistently can help you identify patterns, recognize progress, and address problems before they become more difficult to manage.
Build a Realistic Saving and Investing Plan
Start with financial goals that are specific and achievable. You might aim to establish emergency savings, repay expensive debt, save for a home deposit, or invest for retirement.
Next, decide how much money you can regularly set aside after covering essential expenses and financial obligations.
Consider these steps:
- Set a clear goal: Define what you want to achieve and when you need the money.
- Build a financial buffer: Save an appropriate emergency reserve based on your expenses and circumstances.
- Choose a sustainable savings target: Start with an amount you can maintain and increase it when possible.
- Manage expensive debt: Reduce costly borrowing while meeting other required payments.
- Invest according to your goals: Consider diversification, fees, time horizon, taxes, and risk tolerance.
- Review your plan: Adjust contributions and spending when your financial circumstances change.
Consistency is generally more useful than creating an ambitious plan that becomes impossible to maintain.
Use a Net Worth Tracking Table to Measure Progress
A simple table makes it easier to compare your financial position across months.
| Financial metric | This month | Previous month |
|---|---|---|
| Total assets | $25,000 | $24,000 |
| Total liabilities | $10,000 | $10,500 |
| Net worth | $15,000 | $13,500 |
| Monthly savings | $500 | $400 |
These figures are illustrative examples, not financial benchmarks.
In this example, net worth increased by $1,500, while monthly savings rose by $100. The change in net worth reflects both the increase in assets and the decrease in liabilities.
You can adapt the table to your local currency and financial circumstances. If your net worth falls during a particular month, investigate the reason before drawing conclusions. Investment prices, new borrowing, major purchases, and unexpected expenses can all affect the result.
Conclusion: Take Control of What Determines Personal Wealth
Understanding what determines personal wealth helps you see beyond your salary and focus on the overall condition of your finances.
Income, spending behavior, saving habits, debt management, investments, inflation, and financial knowledge all influence wealth accumulation. Family resources and economic opportunities can also affect how quickly a person builds assets.
Although you cannot control every financial circumstance, you can take practical steps to improve your position. Track your assets and liabilities, develop a realistic spending plan, manage expensive debt, and make informed decisions about saving and investing.
You do not need to transform your finances overnight. Start by calculating your current net worth, identify one area that needs improvement, and review your progress regularly.
Calculate your net worth today and review your progress every month. Small, consistent financial improvements can help you build a stronger foundation for the future.
Frequently Asked Questions About Personal Wealth
Net worth is the value of all included assets minus all liabilities. Liquid net worth focuses on assets that can be converted into cash relatively quickly, minus relevant liabilities. Liquid net worth is useful for understanding how much money may be available to meet near-term needs without selling property or other less-liquid assets.
Generally, yes. Retirement accounts are financial assets and are usually included in net worth calculations. However, withdrawal restrictions, taxes, penalties, and investment fluctuations may affect how much money you can actually access. Check the rules that apply to your particular account and country.
Yes. Your net worth is negative when your total liabilities exceed your total assets. This may happen when someone has substantial education loans, consumer debt, or other obligations but relatively few assets. A negative net worth is a financial snapshot, not a permanent outcome. Tracking changes and developing a realistic repayment and saving plan can help you monitor progress.
Use a reasonable estimate of what your belongings could currently sell for, rather than their original purchase prices. Items such as vehicles, electronics, furniture, and collectibles may lose value over time. Include significant items when appropriate, use conservative estimates, and avoid overvaluing possessions that may be difficult to sell.

“Hi, I am Umer Hasib. I am a passionate blogger and content creator who loves exploring human psychology, social behaviors, and personal growth. Welcome to my inner space!”
Emily Carter
“I always thought earning a higher salary was the main way to build wealth. This article helped me understand why saving consistently and managing debt are just as important.”
“Thanks, Emily! You’re absolutely right. Income creates opportunities, but managing expenses, reducing costly debt, and investing consistently can help turn those earnings into long-term wealth.”
James Anderson
“The net worth calculation table made everything much easier to understand. I’m going to start tracking my assets and liabilities every month.”
“Thank you, James! That’s a great first step. Monthly tracking can help you understand your financial progress and identify areas where small improvements could make a difference over time.”